
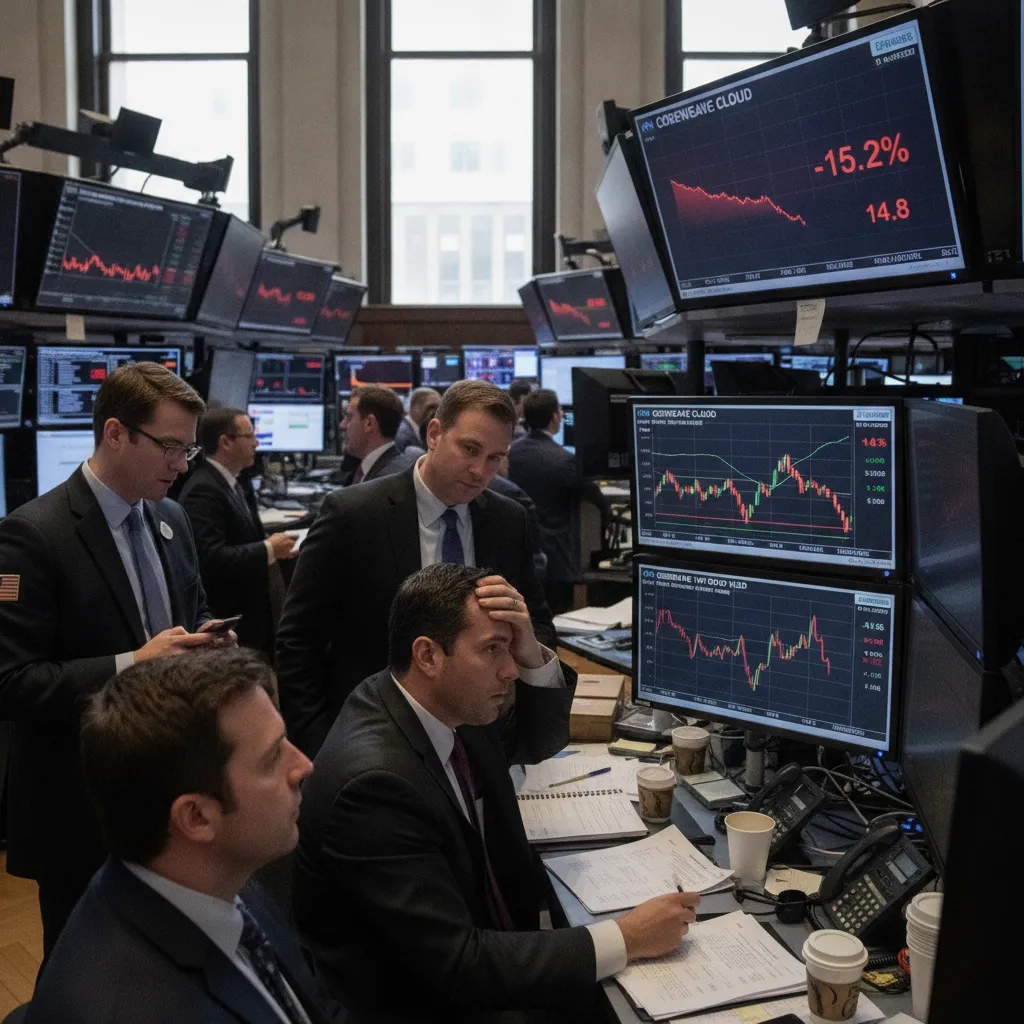
Investors are beginning to question the massive debt piles fueling the artificial intelligence boom, leaving specialized cloud provider CoreWeave caught in a sudden financial storm. On Wednesday, the company saw its shares plummet by more than 15 percent while yields on its long term bonds climbed toward 15 percent. This volatility signals a growing anxiety among traders that the rush to build out AI capacity has led some firms to borrow far beyond their means, turning what was once an exuberant gold rush into a cautious examination of balance sheets.
The selloff gained traction after prominent figures in the tech world highlighted CoreWeave’s precarious position on social media. Tech investor Chamath Palihapitiya pointed to the spiking bond yields as evidence of a potential private credit bubble, drawing a response from Elon Musk that simply read yikes. Analysts suggest that while larger giants like Amazon and Google can absorb massive spending, smaller players lack the fortress balance sheets required to sustain such aggressive expansion during a period of rising interest rates. Some experts describe CoreWeave’s current financials as relatively weak compared to its peers due to its heavy reliance on loans to fund new data centers.
CEO Mike Intrator remained defiant in a memo sent to staff, dismissing the market reaction as irrational behavior common when people misunderstand a developing technology business. He insisted that the company’s order backlog is strong enough to cover all existing debt obligations. Despite this confidence, others see it as part of a broader trend across the tech sector. Other industry names including Dell and Nebius also suffered steep losses on Wednesday, suggesting that investors are no longer handing out cheap capital without scrutiny.
This shift marks the end of an era of easy money for AI startups and mid sized providers who have spent billions racing to secure hardware and power. While total industry spending is projected to eventually top one trillion dollars annually by 2027, the immediate pressure is mounting for those categorized as junk grade borrowers. As markets demand higher risk premiums, companies must now prove they can translate their expensive infrastructure investments into actual profits before their creditors lose patience entirely.